Q: How much money should I have in an emergency fund?
There is something reassuring about having money sitting in an account that you are not planning to spend. The awkward question is how much is enough. You will often hear people mention three months, six months or even a year of expenses, but there is no universal number that makes somebody financially secure.
A more useful starting point is to work out what you actually need to keep paying if your income suddenly disappeared. Think rent or mortgage, council tax, energy, food, essential travel, insurance and important household commitments. Things such as holidays, meals out and subscriptions you could cancel are not really part of the emergency calculation.
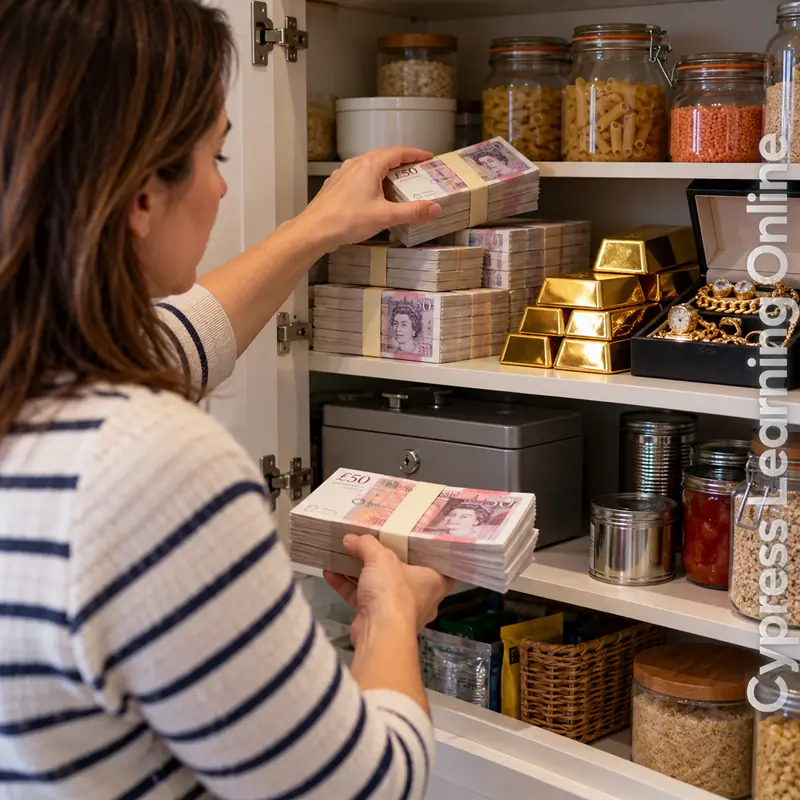
A May 2026 guide from Fidelity suggests three to six months of essential expenses as a common rule of thumb. So if your unavoidable bills come to £1,500 a month, that would mean somewhere between £4,500 and £9,000. That is a useful benchmark, but it is not a commandment.
Your circumstances change the number
Someone with a secure job, two incomes in the household and no dependants may be comfortable with a smaller reserve. Someone who is self-employed, has an irregular income or is supporting children may reasonably want more. If replacing your income would take a long time, the bigger cushion starts to make more sense.
There is also a practical trap here. You do not want to spend years building a huge cash pile while carrying expensive debt at the same time. If you have high-interest credit card borrowing, for example, paying that down can be more valuable than putting every spare pound into savings. It is often sensible to build a small initial buffer first, then tackle expensive debt while continuing to save something.
"Money is a terrible master but an excellent servant." - P.T. Barnum
The other important point is accessibility. An emergency fund is supposed to be available when the boiler breaks, the car needs an unexpected repair or work suddenly disappears. That makes an easy-access savings account more suitable for this particular pot than something designed for long-term investing. You are not trying to maximise returns; you are buying yourself breathing space.
If three to six months sounds completely unrealistic, do not let the target put you off. Start with £500, then £1,000, and keep building. A smaller reserve can still stop an ordinary financial nuisance from immediately becoming expensive borrowing. The right emergency fund is the one that gives you useful protection without making the rest of your finances impossible to manage.
Next Articles
This article was last updated on 2026-07-16. Please see our terms of use. You can find other articles about emergency savings amount using the search function.